Faith First. Integrity Always.
Your deal deserves a straight answer before it needs a lender.
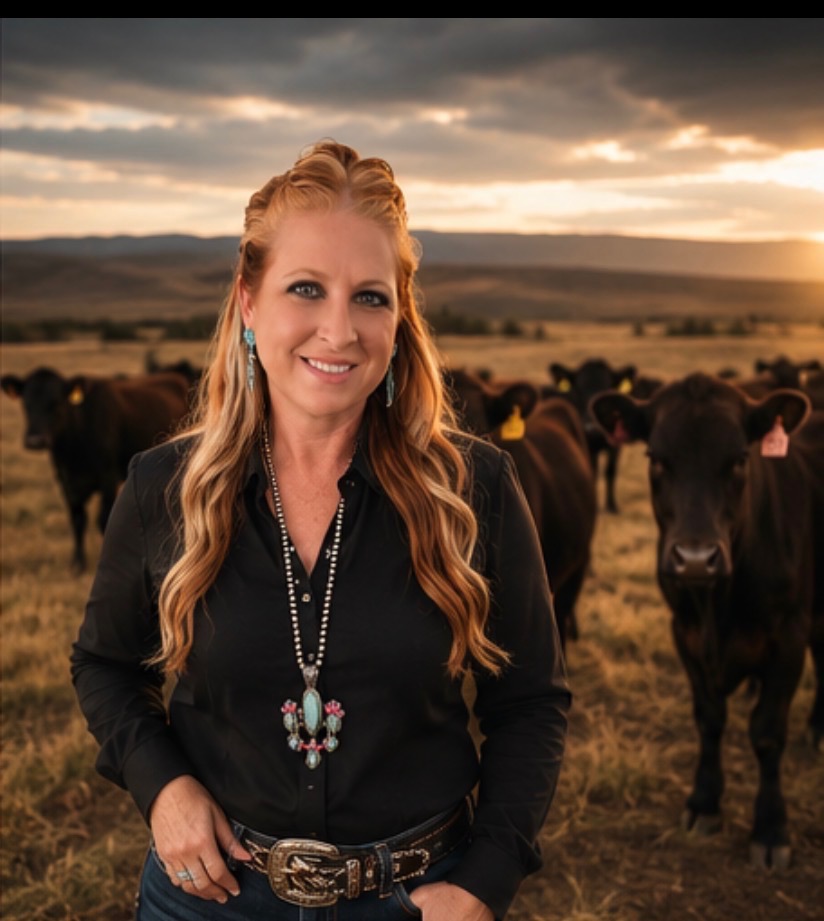
Chandi Langley looks at the whole deal, not just whether it can be placed. She matches real estate investors to the lending partner whose program actually fits the project. If the numbers don't work, she tells you.
Grace & Grit Investors is not a direct lender. Business-purpose real estate financing only.
You found the deal. The funding is the part nobody explains.
Most investors get stuck in the same place. The property makes sense, the plan makes sense, and then the question becomes: who funds this, and what will they need from me? The answers change with every lender and every program.
That's the bridge. Chandi listens to what you're trying to accomplish, reviews the whole deal, and looks for the option that fits the borrower and the project — instead of forcing every deal into the same box.
Funding she can place today
Explore Funding Options →Fix and Flip
Short-term financing to buy and renovate, then sell. Structure and requirements depend on the lender and the deal.
02Rental / DSCR
Longer-term financing for income-producing rentals, weighed mainly on whether the property's income covers the payment.
03New Construction
Ground-up projects, funded in stages. Eligibility depends on the lender, the plan, and your experience.
04Commercial
Financing for commercial property, subject to underwriting, program availability, and property eligibility.
05Bridge
Short-term financing that carries a property from one stage to the next until it sells or moves into permanent financing.
06Cash-Out Refinance Limited
Available for certain commercial and hotel properties only, handled case by case. Not broadly available.
Specialized capital, handled separately
Land development, SBA, hotels, working capital, and large-scale development projects are a different conversation — different scale, different requirements, different timelines. Bring the project and Chandi will tell you whether it belongs in this lane.
Grace & Grit is not a lender
Chandi is the bridge between your deal and a lending partner. She does not underwrite, approve, or fund loans. All financing is subject to lender approval, underwriting, program availability, and property eligibility. Grace & Grit Investors is not a licensed mortgage lender.
No primary residences
All activity is business-purpose real estate financing. Grace & Grit does not offer consumer-purpose financing for owner-occupied primary residences. If the property is your home, this is not the right place — and Chandi will say so on the first call.
How it works
Four steps, and one of them is honesty.
Tell her about the deal
The property, the plan, the numbers you have, and what you're trying to accomplish. A first call runs about 30 minutes.
She reviews the whole deal
Not just whether it can be placed. If there isn't enough profit, or the loan would put you in a bad position, you'll hear that first.
She matches it to a lending partner
Different lenders, different programs. She looks for the one that fits the borrower and the project, then walks you through what it needs.
The lender underwrites and funds
Terms, timing, and approval rest with the lender and depend on the deal. Chandi stays with you through the process.
Deal Readiness Check
Find out what's standing between your deal and lender review.
A short set of questions about the borrower, the property, the financing you're after, and your timeline. You'll get a plain read on whether the deal looks ready — and what would need to change if it isn't. No credit pull, no obligation.
Start Your Deal Review
About Chandi
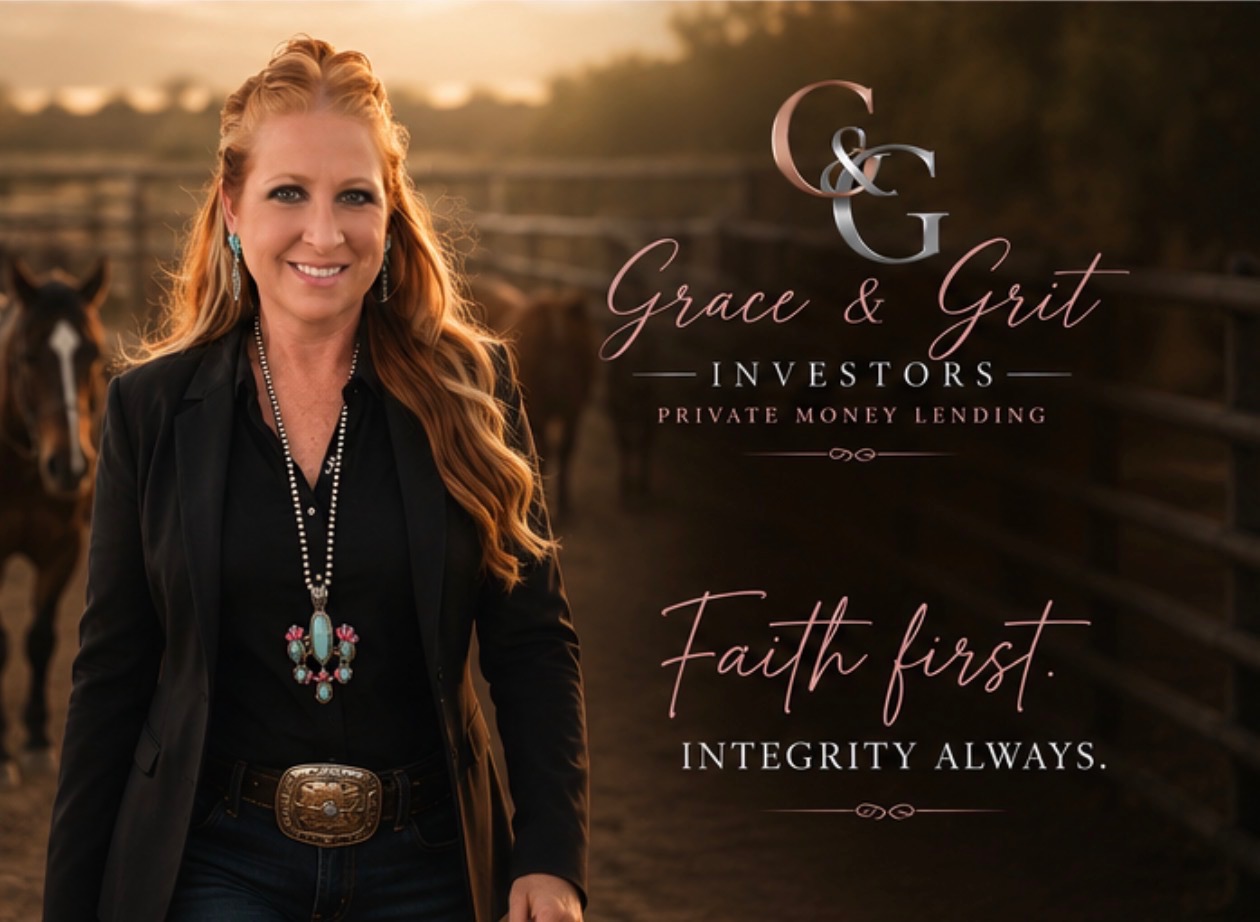
Raised around ranching. Faith first, and God as CEO.
The ranch and rodeo world taught her hard work, resilience, and treating people right. Those are the same values that run the business: Grace is leading with faith and understanding. Grit is doing the work, searching for solutions, and not quitting when a deal is hard.
She wanted to invest herself and had no idea where the funding came from. When she learned she could help fund other investors' deals, she recognized the gap she'd been standing in — and became the bridge. She completed private money lending training and certification, and keeps building lender relationships.
"I'd rather lose a commission than push someone into the wrong loan."
Read her full story →Do I need an LLC to get a fix-and-flip loan? +
Most fix-and-flip lenders require the property to be purchased through a business entity rather than in your personal name. An LLC is the most common option, though some lenders may also accept a corporation or qualifying trust. The exact requirement depends on the lender and program, so Chandi confirms what's needed for your specific deal.
How much cash do I need to bring to a fix-and-flip? +
It depends on the lender, the borrower, and the deal. Even when a program offers up to 100% of purchase price and renovation budget, you may still need money for closing costs, lender fees, prepaid interest, and reserves. She reviews the full deal and helps you understand what you may realistically need.
Do I need good credit for a hard money loan? +
Not always. Requirements depend on the lender and the strength of the deal. Lenders may weigh your credit alongside the property's value, the equity, your experience, and the cash or reserves you can bring. A stronger deal or more available capital may help offset lower credit, but every loan is still subject to lender approval.
What's the difference between a bridge loan and a DSCR loan? +
A bridge loan is short-term financing used to buy, renovate, refinance, or stabilize a property until it can be sold or moved into permanent financing. A DSCR loan is usually long-term financing for a rental, based mainly on whether the property's rental income covers its loan payment and expenses. A bridge loan gets you from one stage to the next; a DSCR loan is built to hold an income-producing property.
Building Legacies. Funding Dreams. Fueling Freedom.
Bring Chandi the deal and get a straight answer.
Text is the fastest way to reach her, then Facebook Messenger, then LinkedIn. First calls are 30 minutes and booked at least 24 hours ahead.
Book a Call
Call or text
505-226-2493Availability
Monday–Friday, 8:00 a.m. – 5:00 p.m. Mountain Time